
Table of Contents
- What Is a Construction Loan and How Does It Work?
- Understanding Progressive Drawdowns and Progress Payments
- Documents Required for Construction Loan Approval
- How Long Does Construction Loan Approval Take?
- Eligibility Requirements and the Application Process
- Managing Your Construction Loan: Budget and Contingency
- From Construction to Permanent Mortgage: Refinancing After Completion
- Conclusion
Last Updated: August 17, 2026
What Is a Construction Loan and How Does It Work?
A construction loan is a type of lending commonly used to fund the construction of a residential property. Rather than all approved funds being advanced at once, funds are generally released progressively as construction reaches agreed stages and lender requirements are satisfied.
During construction, interest is commonly calculated on the amount that has been drawn rather than the full approved facility, although repayment arrangements and loan terms vary between lenders and products.
Construction-loan assessment may involve the borrower’s financial circumstances, building contract, plans and specifications, builder details, project costs, lender valuation and other lender requirements. What happens after construction is completed depends on the particular loan structure and lender terms.
Understanding Progressive Drawdowns and Progress Payments
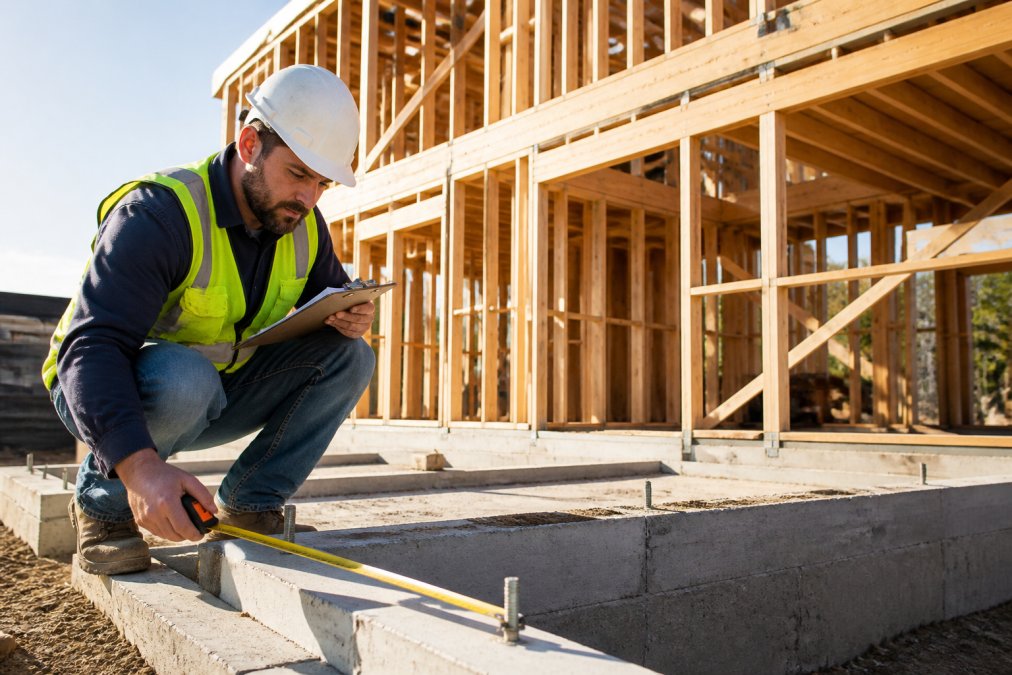
Construction-loan funds are commonly released progressively in line with agreed construction stages and the lender’s requirements.
A builder may submit a progress claim when an agreed stage is reached. Depending on the lender, stage and transaction, the lender may require documents, photographs, a valuation inspection or another form of verification before releasing funds.
Common stages may include slab or base, frame, lock-up, fixing and completion, although terminology and payment schedules vary between building contracts and lenders.
Borrowers should review the progress-payment schedule in their building contract and confirm the lender’s drawdown requirements before construction begins.
How Milestone Completion Triggers Payments
Milestone completion is pivotal in the construction loan process. Common milestones include site preparation, foundation, frame, roof, lockup (weathertight shell), first fix (services installed), second fix (finishing), and practical completion.
The verification process involves your lender’s valuer or independent building inspector visiting the site to confirm the milestone has been reached to contract specifications. If defects or incomplete work are identified, the lender may hold back 5-10% of that drawdown until issues are rectified.
Draw Schedule and Progress Claims
A draw schedule outlines when each payment is released and what percentage each drawdown represents. Typical schedules might allocate: 10% at commencement, 20% at foundation, 15% at frame, 20% at lockup, 15% at first fix, 15% at second fix, and 5% at practical completion.
Progress claims come from your builder, describing work completed since the last claim with photos and trade breakdowns. Your lender reviews claims against the draw schedule and building contract. FinanceCorp recommends reviewing your draw schedule with your builder and lender before signing, so everyone understands the payment timeline and what “completion” means at each stage.
Documents Required for Construction Loan Approval
Construction-loan documentation requirements vary between lenders and projects. Depending on the application, information requested may include:
- building contract
- plans and specifications
- builder details
- building approvals or permits
- site-cost information
- quotes or variation details
- lender valuation
- evidence of available funds
- income, expenses, liabilities and identification information
Additional documents may be required depending on the property, builder, construction method and lender policy.
Deposit and LVR requirements also vary between lenders, borrowers and projects and should not be assumed from a general percentage.
Personal financial documents are standard: recent payslips, tax returns, bank statements, and a list of existing debts. Your lender assesses your ability to repay both interest-only payments during construction and principal and interest payments after conversion.
How Long Does Construction Loan Approval Take?
Processing times vary between lenders and applications. Relevant factors may include the complexity of the borrower’s circumstances, completeness of documentation, valuation requirements, builder and project information, lender workload and whether additional information is requested.
No particular approval or settlement timeframe can be guaranteed. Borrowers should confirm current processing expectations with the lender or broker handling the application.
Eligibility Requirements and the Application Process
Construction loan eligibility hinges on three factors: your financial capacity, the builder’s credentials, and the project’s viability. Most lenders require a minimum 20% deposit of total project cost. Some accept 15% with mortgage insurance, though this adds cost.
Your credit history matters less absolutely than with traditional mortgages. Lenders assess reasons for defaults or late payments. If you’ve recovered financially and demonstrate stable income, many lenders will work with you.
Key Eligibility Criteria
Construction-loan eligibility depends on the borrower, lender, property and construction project. Depending on the application, lenders may consider:
- income and employment or business information
- living expenses and existing liabilities
- credit history
- available deposit or equity
- loan-to-value ratio
- builder and building-contract information
- site and construction costs
- lender valuation
- overall serviceability
Different lenders have different policies regarding builders, construction contracts, deposit requirements, employment types and self-employed applicants.
At the time of publication, APRA requires authorised deposit-taking institutions to apply a mortgage serviceability buffer of at least 3 percentage points above the applicable interest rate for new housing lending. Individual lender policies, assessment methods and permitted exceptions may vary.
Building Contract and Site Costs
Lenders may have requirements regarding the type and content of an acceptable building contract. Contract requirements can differ depending on the lender, builder and construction project.
Borrowers should understand what is included and excluded from the building contract, the progress-payment schedule, potential site costs and how variations are dealt with.
Legal questions about a building contract should be discussed with an appropriately qualified legal or conveyancing professional.
Managing Your Construction Loan: Budget and Contingency
Managing your construction loan budget requires discipline and realistic planning. Start with a detailed project budget including the builder’s contract price, site costs, professional fees (architect, engineer, building inspector), permits and council fees, and a contingency buffer. Professional fees add 5-10% to total project cost and are essential for quality assurance.
Your contingency fund should be 10-15% of total budget. Construction almost always encounters surprises, rock outcrops requiring blasting, soil conditions demanding deeper foundations, or material delivery delays. When contingency runs out, you either delay construction or find additional funds.
Repayments During Construction
Many construction loans involve interest being charged on the funds progressively drawn during construction. The repayment arrangement may be interest-only during some or all of the construction period, depending on the lender and loan terms.
As additional funds are drawn, the amount on which interest is calculated generally increases.
Repayment arrangements after construction vary. Depending on the particular loan, the facility may move to principal-and-interest repayments, remain under an existing loan structure or require another lending step. Borrowers should confirm the post-construction arrangements with their lender or broker.
Contingency Fund and Variations
Variations are changes to building contract scope. Variations must be submitted in writing by the builder with cost and timeline impact. Always get written quotes for variations and review them against your budget before approving. Every variation eats into your contingency and increases cost overrun risk.
If variations exceed your contingency, you have limited options: delay construction while sourcing additional funds, reduce scope elsewhere, or access additional borrowing. The cleanest approach is having sufficient contingency upfront and resisting discretionary variations.
What Happens When Construction Is Completed?
Once construction is complete, the lender may require final documentation or verification before releasing the final progress payment. Requirements vary between lenders and may include a final valuation, completion documentation or confirmation that relevant conditions have been satisfied.
The loan’s repayment arrangements after completion depend on the terms of the particular facility. In some cases, repayment arrangements may change after construction. Refinancing is a separate option and is not automatically required simply because construction has finished.
If a borrower considers refinancing, this involves a new lending assessment and may involve valuation, fees and lender approval.
Conclusion
Construction lending generally involves progressive drawdowns, project documentation, lender assessment and conditions that differ from a standard purchase of an established property.
FinanceCorp provides credit assistance under Australian Credit Licence 395037. FinanceCorp brokers gather information about a consumer’s requirements, objectives and financial situation before explaining and comparing available construction-lending options from the FinanceCorp lender panel. FinanceCorp does not compare every lender or loan product in the market.
Contact FinanceCorp to discuss a construction-loan enquiry, indicative borrowing capacity, lender requirements and available lender-panel options. Any borrowing estimate is indicative only. Any lending recommendation or application remains subject to applicable enquiries, verification, preliminary assessment, lender criteria, valuation requirements and approval.
Frequently Asked Questions
What's the main difference between a construction loan and a standard mortgage?
A construction loan generally releases approved funds progressively as construction reaches agreed stages, while lending for an established property is generally advanced at settlement. Repayment arrangements and lender requirements differ between products.
How do progress payments and invoices work during construction?
Progress claims are generally submitted as construction reaches agreed stages. Depending on the lender, supporting documents, photographs, valuation inspections or other verification may be required before funds are released.
What documents do I need to apply for a construction loan?
Required documents vary between lenders and projects. They may include the building contract, plans and specifications, builder information, approvals, site-cost information, lender valuation and the borrower’s financial and identification information.
How long does construction loan approval usually take?
Processing times vary according to the lender, project and application. Documentation, valuations, builder information, application complexity and lender workload can all affect timing. No particular approval or settlement timeframe can be guaranteed.
This article was written using GrandRanker