
Table of Contents
- What You’ll Need Before Comparing
- Understanding Comparison Rate vs Interest Rate
- Step 1: Gather Your Financial Information
- Step 2: Identify Your Loan Type and Features
- Step 3: Compare Rates Using a Mortgage Comparison Calculator
- Step 4: Review Home Loan Fees and Charges
- How to Compare Mortgage Interest Rates Across Lenders
- Common Mistakes to Avoid When Comparing Rates
Last Updated: August 15, 2026
What You’ll Need Before Comparing
Before comparing home-loan options, it may be useful to gather information about your income, expenses, existing debts, available deposit or equity and the property being purchased or refinanced.
Depending on the lender and borrower circumstances, supporting documents may include payslips, financial statements, tax returns, bank statements, identification and information about existing liabilities. Documentation requirements and applicable time periods vary between lenders.
Borrowers may also wish to consider the proposed loan amount, loan term, repayment type and any loan features they want to understand or compare.
Understanding Comparison Rate vs Interest Rate
The interest rate is the rate charged on the amount borrowed. For relevant fixed-term consumer credit, the comparison rate combines the interest rate with most fees and charges into a single percentage based on a prescribed example loan amount and term.
A comparison rate can assist with comparing the cost of certain credit products, but it does not include every possible fee or charge and does not reflect non-cost features such as offset accounts, repayment flexibility or other product features.
The comparison rate should therefore be considered alongside the advertised interest rate, fees, loan features and the borrower’s proposed loan amount and term.
Step 1: Gather Your Financial Information
When comparing home-loan options, consumers may wish to record information about income, regular living expenses, existing debts and credit limits, savings and available deposit funds.
Lenders assess borrowing capacity using their own serviceability and credit policies. No single calculation of income minus expenses determines the amount a lender will approve.
Consumers may also obtain a copy of their credit report and check whether the information recorded is accurate. If information appears incorrect, the relevant credit reporting body or credit provider can explain the correction process.
Step 2: Identify Your Loan Type and Features
Home-loan rates, features and lender requirements can vary according to loan purpose, repayment type, LVR, loan amount, borrower circumstances and lender pricing policy.
Borrowers may encounter variable-rate, fixed-rate or split-loan arrangements, along with features such as offset accounts, redraw facilities and different repayment frequencies.
The operation, costs and potential effect of these features vary between products. A particular feature should not be assumed to reduce overall borrowing costs without considering fees, balances, repayment behaviour and the terms of the loan.
Step 3: Use Comparison Tools as a Starting Point
Online comparison sites and mortgage calculators may help consumers view advertised rates, comparison rates, estimated repayments and selected loan features.
The lenders and products displayed by a comparison website may not represent every option available in the market, and rankings or filters may be affected by the website’s methodology or commercial arrangements.
Calculator results are estimates based on the information and assumptions entered and are not lending assessments or indications of approval. Current rates, fees and eligibility should be confirmed directly with the relevant lender or broker.
Consumers should also be aware that applications for credit may result in credit enquiries being recorded on their credit report.
Step 4: Review Home Loan Fees and Charges
Home loans may involve application, establishment, package, valuation, settlement, discharge or other fees depending on the lender and product. Some fees may be waived or may not apply to a particular transaction.
Refinancing may also involve costs associated with discharging the existing loan, establishing the new loan and, where relevant, leaving a fixed-rate arrangement early.
Consumers may wish to compare applicable fees alongside the interest rate, comparison rate, loan term, repayment arrangements and product features.
The comparison rate includes most fees and charges for the prescribed example but does not include every possible cost or charge.
Comparing Home-Loan Options Across Lenders
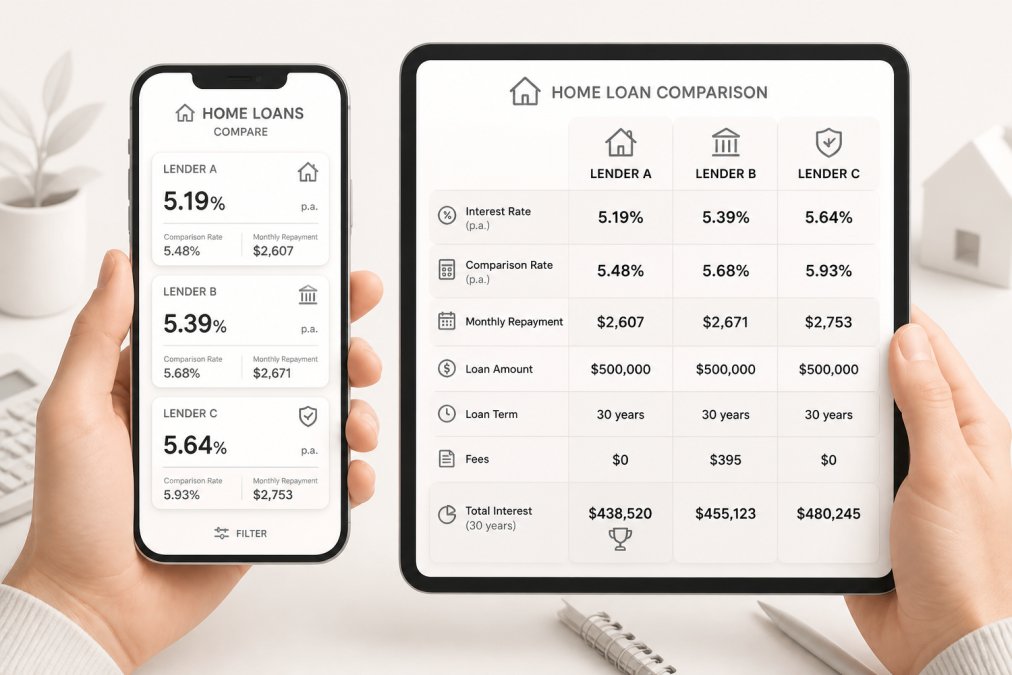
Consumers may compare lenders directly or obtain credit assistance from a mortgage broker. A mortgage broker may compare available options from the lenders on the broker’s accredited panel after gathering information about the consumer’s requirements, objectives and financial situation.
FinanceCorp does not compare every lender or loan product in the market.
When reviewing options, consumers may consider matters such as the applicable interest rate, comparison rate where relevant, fees, repayment arrangements, loan features, lender criteria and the proposed loan term.
Any rate or pricing information should be confirmed at the time of the enquiry, as rates and lender pricing may change. Any lending recommendation or application remains subject to applicable enquiries, verification, preliminary assessment, lender criteria and approval.
Common Considerations When Comparing Home Loans
When comparing home-loan options, consumers may wish to avoid relying on a single factor. Relevant considerations can include:
- the interest rate
- the comparison rate where applicable
- fees and charges
- loan term
- repayment arrangements
- loan features
- lender eligibility requirements
- the borrower’s requirements, objectives and financial situation
The lowest advertised rate does not necessarily result in the lowest overall borrowing cost or mean that a particular loan will meet a borrower’s requirements and objectives.
Rates, product features and lender policies can change, so comparisons should be based on current information.
Comparing Home-Loan Options
Comparing home loans involves more than looking at the advertised interest rate. The comparison rate where applicable, fees, loan term, repayment arrangements, features, lender policies and the borrower’s circumstances may all be relevant.
FinanceCorp provides credit assistance under Australian Credit Licence 395037. FinanceCorp brokers gather information about a consumer’s requirements, objectives and financial situation before explaining and comparing available options from the FinanceCorp lender panel. FinanceCorp does not compare every lender or loan product in the market.
Contact FinanceCorp to discuss a home-loan enquiry and available lender-panel options. Any borrowing estimate is indicative only. Any lending recommendation or application remains subject to applicable enquiries, verification, preliminary assessment, lender criteria and approval.
Important information: This article provides general information for educational purposes only. It does not take into account your objectives, financial situation, needs or borrowing requirements and is not a recommendation to select a particular loan feature, refinance, use a comparison website, approach a particular lender or apply for any particular loan or credit arrangement.
FinanceCorp provides credit assistance under Australian Credit Licence 395037. The lenders and products considered depend on broker accreditation, lender-panel access, the type of lending requested, the information provided and the consumer’s circumstances. FinanceCorp does not compare every lender or loan product in the market.
Interest rates, comparison rates, fees, loan features, lender policies, eligibility requirements and product availability vary between lenders and may change. Online comparison results, calculators and examples are illustrative only and may not reflect all lenders, products, fees or individual circumstances.
A comparison rate does not include every possible cost and only provides a cost comparison based on the prescribed assumptions used to calculate it.
Any borrowing estimate is indicative only. Any credit assistance, lending recommendation or application remains subject to applicable enquiries, verification, preliminary assessment, lender criteria, approval, terms, conditions, fees and charges.
Frequently Asked Questions
What is the difference between a comparison rate and an interest rate?
The interest rate is the rate charged on the amount borrowed. For relevant fixed-term consumer credit, a comparison rate combines the interest rate with most fees and charges based on a prescribed example amount and term. It does not include every possible cost and should be considered alongside loan features and other applicable charges.
How do I use a mortgage comparison calculator to compare mortgage interest rates?
A mortgage calculator can provide illustrative repayment estimates based on the loan amount, interest rate and term entered. Calculator results are estimates only and are not a lender assessment or indication of approval or actual future repayments.
What home loan fees and charges should I look for when comparing rates?
Fees vary between lenders and products and may include establishment, package, valuation, settlement, discharge or other charges. Consumers should confirm the fees applying to the particular loan.
Should I compare mortgage interest rates myself or use a broker?
Consumers can compare lender information themselves or obtain credit assistance from a mortgage broker. A broker may compare available options from their accredited lender panel. The most appropriate approach will depend on the consumer’s preferences and circumstances. Broker commissions and any consumer fees should be disclosed where applicable.
This article was written using GrandRanker