
Table of Contents
- What Mortgage Broker Assistance for First Buyers Actually Covers
- First Home Buyer Government Grants Australia: What’s Available
- Saving for a Deposit and Understanding Your Borrowing Capacity
- Lenders Mortgage Insurance (LMI) Explained for First-Time Buyers
- The Mortgage Pre-Approval Process Australia: Step by Step
- Mortgage Broker Fees for First Home Buyers: What You Pay
- From Pre-Approval to Settlement: The Full Home Buying Journey
- Conclusion
Last Updated: August 7, 2026
What Mortgage Broker Assistance for First Buyers Actually Covers
Mortgage broker assistance for first buyers is a guided, end-to-end service that helps you understand your borrowing capacity, access government grants, navigate lender requirements, and reach settlement with confidence. For most first-time buyers, the process involves more moving parts than expected, and the cost of a misstep is significant.
At FinanceCorp, we have spent more than 26 years guiding Australians through this process. Our team works with a panel of over 25 lenders and hundreds of loan products, meaning the advice you receive is not shaped by what a single bank offers that month.
Broker vs. Going Direct to a Lender: What Changes
Going direct to a bank means you see one lender’s products. A broker sees the full panel. A broker assesses your financial position, identifies which lenders are most likely to approve you, and structures your application to present you in the strongest light. Many first buyers have non-standard income, minimal credit history, or a deposit just below a key threshold. A broker knows which lenders are flexible on those points and manages paperwork, communicates with the lender on your behalf, and flags issues before they become rejections.
First Home Buyer Government Grants Australia: What’s Available
Australia offers several government schemes designed to reduce the upfront cost of buying a first home. Schemes change regularly and eligibility varies by state and territory, so checking the official source before applying is essential.
First Home Owner Grant (FHOG)
The First Home Owner Grant is a one-off payment available to eligible first home buyers purchasing or building a new home. Each state and territory administers its own version with different amounts and eligibility thresholds depending on where you buy and property value.
To qualify, you generally must be an Australian citizen or permanent resident, be buying or building a new home (not established property in most states), and meet your state’s property value cap. You must not have previously owned a home in Australia. Applications are typically lodged through an approved agent, often your lender or broker, at settlement or first drawdown for a construction loan.
Check the current grant amount and eligibility criteria for your state through the Australian Government’s First Home Owner Grant information.
Stamp Duty Exemptions and Concessions
Stamp duty is one of the largest incidental expenses a first buyer faces. Most states and territories offer either a full exemption or a concession for first home buyers, depending on purchase price and whether the property is new or established. The threshold at which duty kicks in and the rate at which it scales differs significantly across jurisdictions. A broker familiar with your target market can explain which concession applies and how to factor it into your budget.
Shared Equity and Federal Guarantee Schemes
The federal government’s Home Guarantee Scheme allows eligible first buyers to purchase with a smaller deposit without paying Lenders Mortgage Insurance. The scheme has several streams, including options for single parents and regional buyers, each with its own income caps and property price limits.
Some state governments operate shared equity schemes where the government takes a partial equity stake in the property, reducing the amount you need to borrow. These are particularly useful in high-cost markets where saving a full deposit takes years.
For current scheme details and place availability, refer to Housing Australia’s Home Guarantee Scheme information.
Saving for a Deposit and Understanding Your Borrowing Capacity
The standard deposit requirement for a home loan in Australia is 20% of the purchase price, which avoids Lenders Mortgage Insurance. Many first buyers cannot reach that threshold quickly, and strategy matters.
Most lenders will accept a deposit as low as 5% if you qualify under a government guarantee scheme or are willing to pay LMI. The First Home Super Saver Scheme allows eligible buyers to make voluntary contributions into their superannuation fund and withdraw them for a deposit, taking advantage of concessional tax treatment inside super. Check current withdrawal limits and eligibility rules through the Australian Taxation Office’s First Home Super Saver Scheme guidance.
Borrowing capacity is calculated differently by every lender, taking into account gross income, existing debts, living expenses, dependants, and loan structure. A broker runs this assessment across multiple lenders before you apply, so you know your realistic ceiling before bidding. Closing a credit card you don’t use can meaningfully increase your borrowing capacity, because lenders assess the full limit as potential debt, not just the outstanding balance.
Request a copy of your credit report before approaching any lender. Errors on credit files are common, and correcting one can take several weeks. Getting ahead of this avoids delays at pre-approval.
Lenders Mortgage Insurance (LMI) Explained for First-Time Buyers
Lenders Mortgage Insurance is a one-off premium paid by the borrower when the deposit is below 20% of the property value. LMI protects the lender, not the buyer, in the event of default. The premium scales with the loan-to-value ratio and loan amount.
A broker can model both scenarios, paying LMI now versus waiting to save a larger deposit, using current property price trends in your target area, your savings rate, and current interest rates. If you qualify under the Home Guarantee Scheme, LMI is waived entirely, which is one of the most significant financial benefits the scheme provides.
The Mortgage Pre-Approval Process Australia: Step by Step
Pre-approval is a conditional assessment by a lender confirming they are willing to lend you up to a specified amount, subject to property valuation and your financial position remaining unchanged. It gives you a credible budget when making offers.
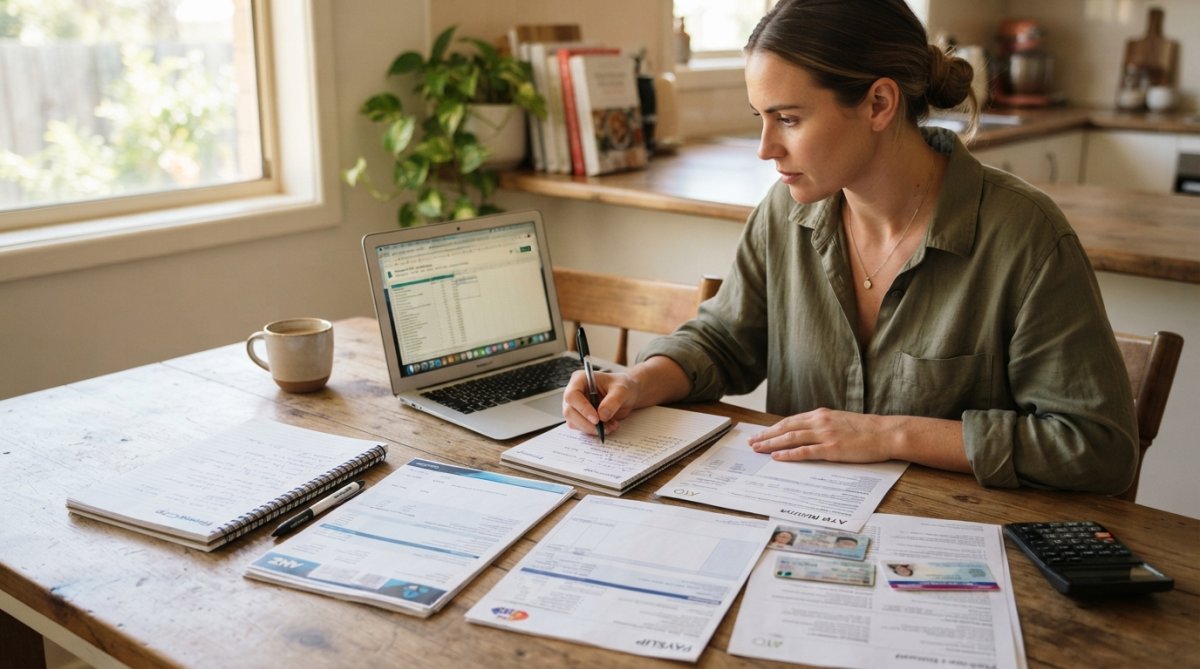
The pre-approval process typically follows these steps:
- Assess your financial position. Calculate your income, existing debts, monthly expenses, and deposit amount. Identify which government schemes you may qualify for.
- Check your credit history. Obtain your credit report and address any errors or outstanding defaults before applying.
- Engage a broker or lender. A broker will identify the most suitable lenders for your situation and recommend a loan structure.
- Prepare and submit your application. Compile supporting documents and submit through your broker or directly to the lender.
- Receive conditional approval. The lender issues a pre-approval letter, typically valid for 90 days, specifying the approved amount and conditions.
- Begin your property search. With pre-approval in hand, you can make offers with confidence and move quickly when the right property appears.
Documents You’ll Need to Prepare
Lenders require a consistent set of documents regardless of which institution you apply with. Having these ready before you start saves time and avoids delays:
- Recent payslips covering the last two to three months
- The last two years of tax returns and ATO notices of assessment
- Bank statements for all accounts, typically covering three to six months
- Proof of your deposit, including savings history and any gift letters
- Government-issued photo identification
- Details of any existing debts, including credit cards, personal loans, and HECS-HELP balances
- Rental history if you are currently renting
Do not apply for new credit cards, personal loans, or buy-now-pay-later accounts while your home loan application is in progress. New credit enquiries appear on your file and can affect both your credit score and borrowing capacity assessment.
Credit History and How to Strengthen It Before You Apply
A clean credit history is a baseline requirement for most lenders. Common issues on first buyer credit files are missed utility payments, telecommunications defaults, and multiple credit enquiries from comparison shopping.
Practical steps to strengthen your credit profile before applying:
- Pay all bills on time for at least six months before lodging your application
- Reduce credit card limits to only what you need
- Avoid applying for any new credit products in the six months before your home loan application
- Check your credit file through a free service and dispute any errors immediately
Mortgage Broker Fees for First Home Buyers: What You Pay
In Australia, mortgage brokers are typically paid a commission by the lender when a loan settles. This means most first buyers pay nothing directly to their broker for the initial loan application and settlement. The commission structure is regulated under the best interests duty obligations introduced by the National Consumer Credit Protection Act, which requires brokers to act in the client’s best interests rather than in favour of lenders who pay higher commissions.
FinanceCorp’s fee structure is discussed openly at the outset. If any fee applies to your situation, you will know about it before any work begins. Ask any broker two direct questions: what commission do you receive from the lenders on your panel, and do any lenders pay you more than others?
| What First Buyers Typically Pay | When It Applies |
|---|---|
| Broker service fee | Varies by broker; many charge nothing for standard applications |
| Lender application fee | Charged by some lenders at application or settlement |
| Lenders Mortgage Insurance | Applies when deposit is below 20% (waived under some government schemes) |
| Stamp duty | Varies by state; exemptions and concessions apply for first buyers |
| Conveyancing fees | Paid to your solicitor or conveyancer at settlement |
| Building and pest inspection | Recommended before exchanging contracts |
| Property valuation fee | Some lenders charge this; others absorb the cost |
From Pre-Approval to Settlement: The Full Home Buying Journey
Pre-approval is the starting line, not the finish. Once you find a property and your offer is accepted, your broker orders a formal property valuation. The lender uses this to confirm the loan-to-value ratio and issue unconditional approval. Your conveyancer or solicitor reviews the contract, conducts title searches, and manages the exchange of contracts. A cooling-off period applies in most states, giving you a window to withdraw if significant issues emerge from inspections.
Settlement is the day the loan funds are transferred to the vendor and ownership passes to you. Your broker coordinates with the lender to ensure funds are ready. Your conveyancer handles the legal transfer and registers the property in your name.
Incidental Expenses and Settlement Costs to Budget For
First buyers consistently underestimate costs beyond the deposit and purchase price. These settlement costs are real and need to be in your budget before you sign anything:
- Stamp duty: The largest variable cost; check your state’s first buyer concession
- Conveyancing: Legal fees for the transfer of title
- Building and pest inspection: Essential before exchanging contracts on an established property
- Loan establishment fees: Some lenders charge an upfront fee to set up the loan
- Council and water rates adjustments: Pro-rated at settlement based on the settlement date
- Moving costs: Often overlooked until the week before settlement
Budget for incidental expenses equivalent to a meaningful percentage of your purchase price on top of your deposit. Your broker and conveyancer can give you a more precise figure once the purchase price is known.
Post-Purchase Financial Planning
Your loan structure, repayment frequency, and offset account strategy will determine how quickly you build equity and how much interest you pay over the life of the loan. Making fortnightly repayments instead of monthly results in one additional full repayment per year, which compounds meaningfully over a 25-to-30-year loan term.
An offset account linked to your home loan reduces the balance on which interest is calculated. Every dollar sitting in that account effectively earns the same rate as your home loan interest rate, tax-free. Review your loan structure annually, as a product that was competitive at settlement may not be the best option two years later. FinanceCorp’s team supports clients beyond settlement, including refinancing reviews when circumstances change.
The most valuable thing a mortgage broker provides is the ability to structure your application, your loan, and your ongoing repayment strategy to match your actual financial situation, not a generic template.
Mortgage broker assistance for first buyers covers far more ground than most people realise before they start. The combination of government grants, stamp duty concessions, shared equity schemes, and the right loan structure can make a material difference to how quickly you enter the market and how comfortably you manage repayments. FinanceCorp has been helping Australian first buyers navigate this process for more than 26 years, with access to over 25 lenders and hundreds of loan products to match every situation.
Enquire today and let the FinanceCorp team build a clear, personalised path to your first home.
Frequently Asked Questions
Do mortgage brokers charge first home buyers a fee?
Most mortgage brokers in Australia are paid a commission by the lender when your loan settles, which means many first home buyers pay nothing directly to the broker. However, some brokers do charge an application or advice fee depending on the complexity of your situation. Always ask upfront about the full fee structure before you proceed. A broker must disclose how they are paid under their obligations as an Australian Credit Licensee or Credit Representative, so you can compare the true cost of using a broker versus going direct.
What government grants are available for first home buyers in Australia?
First home buyers in Australia may be eligible for the First Home Owner Grant (FHOG), which is administered by each state and territory government and generally applies to new or substantially renovated homes. Federal schemes such as the First Home Guarantee allow eligible buyers to purchase with a smaller deposit without paying Lenders Mortgage Insurance. Stamp duty exemptions and concessions are also available in most states. Eligibility criteria, grant amounts and property price caps vary by state, so check your state revenue office or speak with a mortgage broker for current figures.
How does a mortgage broker help with the First Home Guarantee?
A mortgage broker can confirm whether you meet the eligibility criteria for the First Home Guarantee, identify which participating lenders on their panel are approved to offer the scheme, and manage your application end to end. Because places in the scheme are limited each financial year, a broker who monitors allocations closely can help you apply at the right time. They also compare loan structures across approved lenders so you are not simply placed with the first available option, which matters when interest rates and loan features vary between lenders.
What should I ask a mortgage broker as a first home buyer?
Ask how many lenders are on their panel and whether they include the major banks and specialist lenders. Ask how they are paid and whether any lender pays them a higher commission. Ask which government schemes you are eligible for and what your realistic borrowing capacity is based on your current income and credit history. Ask what the loan-to-value ratio means for your deposit and whether LMI applies. Finally, ask what the full timeline looks like from pre-approval through to settlement, including what incidental expenses you should budget for beyond the purchase price.
This article was written using GrandRanker