
Table of Contents
- What Is LVR in Home Loans?
- How to Calculate LVR
- Why LVR Matters for Your Home Loan
- Lenders Mortgage Insurance (LMI) Explained
- Impact of LVR on Interest Rates
- How to Lower Your LVR Before Applying
- LVR Thresholds and Lender Requirements
- Conclusion
Last Updated: August 11, 2026
What Is LVR in Home Loans?
Loan-to-value ratio (LVR) is the percentage of a property’s value that you borrow as a home loan. It’s calculated by dividing the loan amount by the property’s valuation and expressing it as a percentage. If you’re buying a property valued at $500,000 and borrowing $400,000, your LVR is 80%.
LVR is one factor lenders may consider when assessing a home-loan application. It can affect lender eligibility, available loan products, pricing and whether Lenders Mortgage Insurance or another risk fee may apply. Other factors, including income, expenses, liabilities, credit history, property type and lender policy, may also affect the available lending options.
How to Calculate LVR
Calculating your loan-to-value ratio is straightforward once you have two numbers: the loan amount and the property valuation.
Step-by-step calculation
Follow these steps to work out your LVR:
- Determine the property valuation. This is the value the lender’s valuer assigns to the property, not the purchase price.
- Establish your loan amount. This is the amount of lending being assessed for the transaction and may differ from simply subtracting the cash deposit from the purchase price.
- Divide the loan amount by the property valuation.
- Multiply by 100 to convert to a percentage.
The formula is: (Loan Amount ÷ Property Valuation) × 100 = LVR %
Real example
You’re buying a property for $600,000 with a $120,000 deposit, so you need to borrow $480,000. The lender’s valuer assesses the property at $600,000.
($480,000 ÷ $600,000) × 100 = 80% LVR
Now consider a scenario where the property is valued at $580,000 instead:
($480,000 ÷ $580,000) × 100 = 82.76% LVR
A lower valuation increases your LVR because you’re borrowing a larger percentage of the property’s assessed value.
Why LVR Matters for Your Home Loan
LVR is one of several factors lenders may consider when assessing a home-loan application and determining available products, pricing and security requirements.
Different lenders use different LVR limits and pricing tiers. In some cases, a lower LVR may provide access to different rates or products, while higher-LVR lending may involve additional lender requirements, Lenders Mortgage Insurance or other risk fees.
Borrowing capacity is assessed separately and may depend on factors including income, expenses, liabilities, dependants, credit history, lender serviceability requirements and the proposed loan.
If a borrower refinances or seeks additional lending later, the lender may obtain a new property valuation and reassess the applicable LVR under its current policies.
Lenders Mortgage Insurance (LMI) Explained
Lenders Mortgage Insurance generally protects the lender if a borrower defaults and the proceeds from selling the security property are insufficient to repay the outstanding debt. It does not protect the borrower.
When LMI May Apply
Whether LMI applies depends on the lender, LVR, loan type, borrower circumstances and any applicable lender or government scheme. Some lenders may require LMI for higher-LVR lending, while different thresholds, waivers or eligibility arrangements may apply.
Eligible borrowers using the Australian Government 5% Deposit Scheme can purchase an eligible home with a minimum 5% deposit without paying Lenders Mortgage Insurance, subject to the Scheme requirements and participating-lender approval.
How LMI May Affect Loan Costs
Where LMI applies, the premium may be payable upfront or, where permitted, added to the loan. If the premium is capitalised into the loan, interest may also be charged on that amount. The premium and available payment arrangements vary between lenders, insurers and borrowers.
If a borrower defaults and a shortfall remains after the secured property is sold, the borrower may remain liable for that shortfall subject to the applicable arrangements.
How LVR May Affect Loan Pricing
Some lenders use LVR-based pricing tiers, which means the interest rate or available product may vary depending on the applicable LVR.
Pricing policies differ between lenders and may also depend on factors including loan amount, repayment type, property type, loan purpose, product features and borrower circumstances.
A lower LVR does not guarantee a particular interest rate or product. Current rates and eligibility should be confirmed at the time of the lending enquiry.
Factors That Can Affect LVR
LVR is affected by the amount borrowed and the value the lender uses for the security property. Factors that may affect the resulting LVR include:
- the proposed loan amount
- the borrower’s cash contribution
- the property purchase price
- the lender’s valuation
- any amounts added to the loan, where permitted
A larger cash contribution or lower proposed loan amount may result in a lower LVR, while a lender valuation below the purchase price may result in a higher LVR.
Property valuations are determined under lender and valuer processes and cannot be guaranteed or controlled by the borrower.
Borrowers should also consider their available cash, other financial commitments and overall borrowing requirements rather than focusing only on achieving a particular LVR.
LVR Thresholds and Lender Requirements
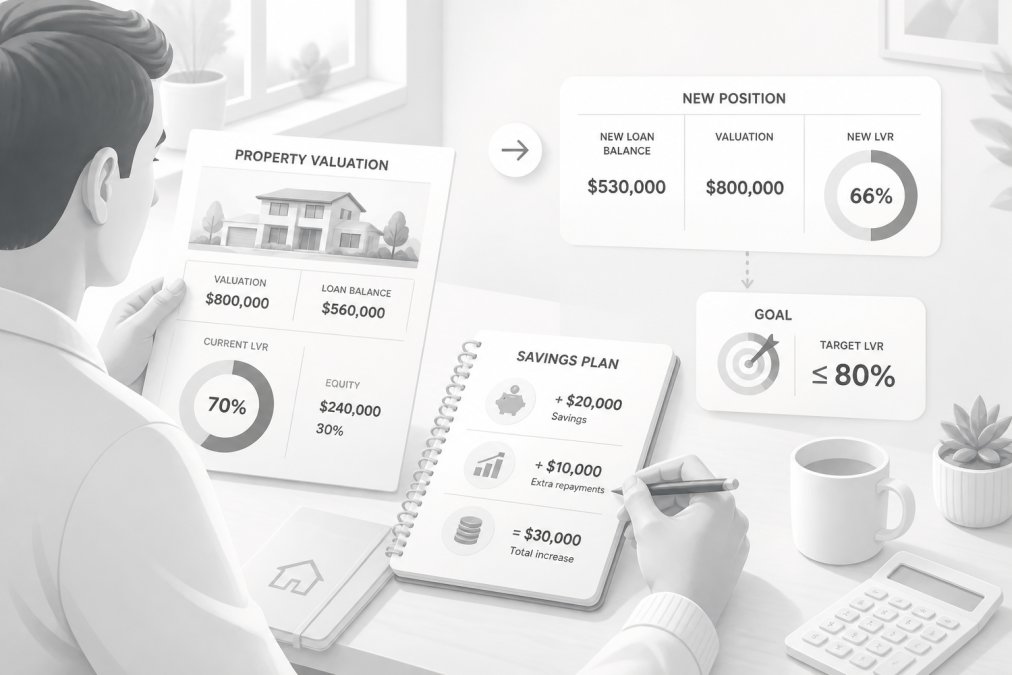
Maximum LVRs and LVR-based pricing thresholds vary between lenders, loan purposes, property types and borrower circumstances.
Different requirements may apply to owner-occupied lending, investment lending, construction loans and other lending scenarios. Higher-LVR applications may also be subject to additional lender, insurer or guarantor requirements.
Government home-buyer schemes can also affect the deposit and LMI requirements for eligible borrowers. For example, the Australian Government 5% Deposit Scheme allows eligible first-home buyers to purchase with a minimum 5% deposit without LMI, subject to property price caps, Scheme eligibility and participating-lender approval.
The maximum LVR available to a particular borrower should therefore be confirmed with the relevant lender or broker rather than assumed from a general percentage.
Understanding LVR can help borrowers interpret how the proposed loan amount and lender valuation interact and why different lenders may have different requirements.
FinanceCorp provides credit assistance under Australian Credit Licence 395037. FinanceCorp brokers gather information about a consumer’s requirements, objectives and financial situation before explaining and comparing available options from the FinanceCorp lender panel. FinanceCorp does not compare every lender or loan product in the market.
Contact FinanceCorp to discuss a home-loan enquiry, indicative borrowing capacity, LVR considerations and available lender-panel options. Any borrowing estimate is indicative only. Any lending recommendation or application remains subject to applicable enquiries, verification, preliminary assessment, lender criteria and approval.
Frequently Asked Questions
What is a good LVR for a home loan?
A lower LVR is generally better because it reduces your lender's risk and improves your loan terms. Most lenders prefer an LVR of 80% or below, which means you have at least a 20% deposit. An LVR below 60% typically qualifies you for the best interest rates and avoids Lenders Mortgage Insurance entirely. However, what's 'good' depends on your financial situation, the property market conditions, and your lender's requirements. First-home buyers often work with higher LVRs initially and aim to reduce them over time through repayments and property appreciation.
How is LVR calculated for a property purchase?
LVR is calculated by dividing your loan amount by the property's valuation, then multiplying by 100 to get a percentage. For example, if you're borrowing $360,000 and the property is valued at $500,000, your LVR is 72%. The property valuation comes from an independent valuer appointed by your lender, not from the asking price or your own estimate. Your deposit size directly affects your LVR: a larger deposit means a lower loan amount and therefore a lower LVR, which improves your borrowing position.
What does 90% LVR mean for borrowers?
An LVR of 90% means you're borrowing 90% of the property's value and providing a 10% deposit. This is a high LVR that signals greater risk to lenders because you have less equity in the property. At 90% LVR, you'll almost certainly pay Lenders Mortgage Insurance, which adds to your loan cost. You'll also face higher interest rates than borrowers with lower LVRs. While 90% LVR is achievable for first-home buyers, it's worth exploring ways to reduce it before applying, such as saving a larger deposit or finding a lower-priced property.
Does a lower LVR mean a better interest rate?
Yes, a lower LVR typically results in a better interest rate. Lenders view lower LVRs as lower risk because you have more equity in the property, so they reward you with more competitive rates. The difference can be significant: borrowers with an LVR of 60% or below often receive substantially better rates than those at 85% or 90%. Beyond the interest rate itself, a lower LVR also means you may avoid Lenders Mortgage Insurance entirely, which saves you thousands over the life of your loan. This is why improving your LVR before applying is a worthwhile investment of time and effort.
This article was written using GrandRanker